MiCA Does Not Regulate DeFi: The Legal Vacuum Surrounding Decentralized Finance
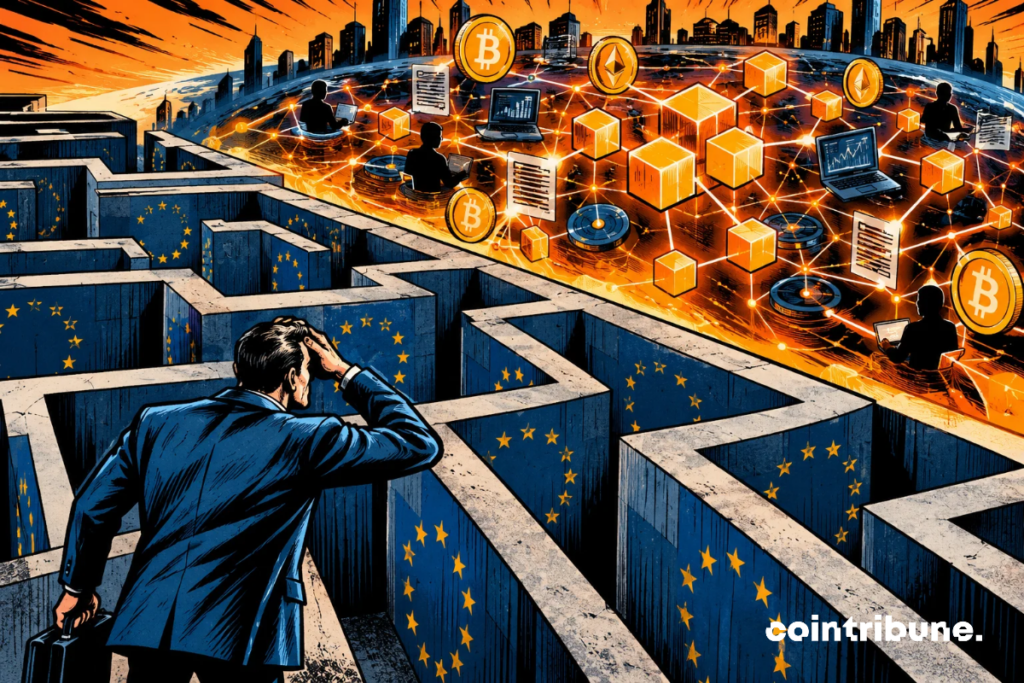
MiCA has been fully applicable since July 1, 2026: any crypto platform that serves European clients must be licensed under penalty of illegality. But the regulation stops at the door of decentralized finance (DeFi). A user of Uniswap or Aave is not protected by any of its rules and does not always know it. The European framework is now the only one in force. But MiCA does not regulate decentralized finance (DeFi), and this boundary was intentionally drawn by the regulation.
In brief
- Since July 1, 2026, MiCA requires a license for crypto platforms serving EU clients, except for fully decentralized services.
- According to the EBA and ESMA, DeFi represents about 4% of the crypto market and few protocols are truly decentralized.
- Users of truly decentralized protocols have little recourse, while the European Commission is studying future regulation.
What MiCA exactly says about DeFi
The fate of decentralized finance is contained in a single sentence of the European text. Recital 22 of the Regulation (EU) 2023/1114 specifies that when crypto-asset services are provided in a fully decentralized manner without any intermediary, they do not fall under the scope of MiCA. No identifiable intermediary, no licensing requirement, no conduct rules.
The same recital immediately sets the opposite limit: MiCA applies as soon as a natural or legal person carries out, provides, or controls an activity, directly or indirectly,
including when part of these activities or services is carried out in a decentralized manner.
In other words, the exemption only applies to total decentralization, with no actor behind it.
The significant detail is that this exemption appears only in the preamble. The articles of MiCA do not define anywhere what a “fully decentralized” service is. Thus, the boundary is set without instructions for use.
Why almost no DeFi is truly “fully decentralized”
This is where the gap partly closes. In a joint report submitted under Article 142 of MiCA on January 16, 2025, the EBA and ESMA conclude:
DeFi remains a niche phenomenon.
DeFi remains a niche phenomenon, with locked value equivalent to about 4% of the global crypto market capitalization. The two authorities add that very few systems reach the total decentralization targeted by recital 22.
In practice, most protocols presented as decentralized retain identifiable actors: known developers, concentrated governance, administration keys, update rights, entities animating the ecosystem. A user’s journey almost always passes through a point of attachment: a web interface, a bridge, a stablecoin issuer; behind which someone is.
The TVL (total value locked) of global DeFi is approximately $86.2 billion as of the date of this article.
The consequence is twofold and counterintuitive. On one hand, a truly intermediary-free protocol escapes MiCA, leaving the user with no regulated counterparty. On the other, as soon as an identifiable entity controls or operates the service, MiCA can apply, and the “it’s DeFi, so it’s unregulated” becomes a legal trap. ESMA itself acknowledges this: the exact scope of the exemption remains uncertain and is assessed case by case.
What this concretely changes for a European user
The dividing line is that of protection. Faced with a licensed platform (PSCA / CASP), the user benefits from a framework: segregation of funds, controlled governance, complaint mechanism, supervision by a national authority. Faced with a truly decentralized protocol, they have none of these: no interlocutor, no recourse with their regulator in case of loss, smart contract bug, or liquidity drain.
Two points that most users ignore. First, the absence of a MiCA framework does not eliminate taxation: gains remain taxable according to the rules of each country. Second, the DeFi exemption does not protect against scams: national authorities continue to blacklist fraudulent sites claiming to be “decentralized,” and providing a crypto service without authorization remains an offense in the Union.
MiCA and DeFi: What Brussels is preparing
The blind spot is acknowledged, and its review is scheduled. Article 142 of MiCA mandates the European Commission to evaluate the development of decentralized finance and the opportunity to regulate it. The January 2025 joint EBA/ESMA report laid the empirical groundwork.
In 2026, the Commission launched a consultation whose orientation is revealing: it is not primarily seeking to regulate fully decentralized protocols as such, but to determine whether responsibility can be attached to identifiable persons who exercise influence over a protocol, or to regulated intermediaries who facilitate access. The logic is not to chase after the code, but to find, wherever possible, an actor to hold accountable. Meanwhile, only platforms already licensed under MiCA currently offer a complete framework to the user.
To date, no date has been announced for its conclusions. Until then, the recital 22 exemption remains the only rule applicable to decentralized finance, a principle enshrined in a simple preamble, never in the articles, for a sector that already weighs 4% of the global crypto market.
Maximize your Cointribune experience with our "Read to Earn" program! For every article you read, earn points and access exclusive rewards. Sign up now and start earning benefits.
Spécialisé dans le mining et le Proof of Work, les altcoins, les marchés crypto et la couverture d'événements du secteur (salons, conférences Web3). Passionné par l'adoption de la blockchain et la réglementation, je m''attache à décrypter ce que chaque actualité change concrètement pour le lecteur, avec un regard technique et précis sur le matériel comme sur les marchés.
The views, thoughts, and opinions expressed in this article belong solely to the author, and should not be taken as investment advice. Do your own research before taking any investment decisions.